If you own a home in Florida, you’ve probably heard the words “wind mitigation inspection” at some point during the insurance process. Maybe you had one completed when you purchased your home. Maybe your insurance agent asked for one. Or perhaps you have a report sitting in your files and aren’t quite sure what it actually means.
A wind mitigation inspection isn’t the same thing as a general home inspection, and it isn’t simply a pass-or-fail test. Its purpose is to document certain features of a home that may help it withstand wind damage. For Florida homeowners, understanding that report can be worthwhile, particularly when purchasing a home, replacing a roof, making improvements, or reviewing homeowners insurance.
What Is a Florida Wind Mitigation Inspection?
A wind mitigation inspection looks at specific construction features that may affect how a home performs during high-wind events. The inspector documents those features on the applicable inspection form and typically takes photographs to support the findings. The report can then be provided to an insurance professional or insurer as part of the homeowners insurance process. Unlike a traditional home inspection, the inspector isn’t primarily looking for every maintenance issue or defect in the house. The focus is much narrower: features related to wind resistance.
What Does the Inspector Look For?
The exact findings depend on the individual property, but a wind mitigation inspection generally evaluates several important characteristics of the home.
These may include:
- The age of the home and applicable building code information
- The age and type of roof covering
- How the roof deck is attached to the structure
- The connection between the roof and the walls
- The shape of the roof
- Secondary water resistance, when applicable
- Protection of windows, doors, and other openings
Why do these details matter? Because during a major wind event, the way a roof, walls, doors, and windows are constructed and connected can affect how the structure responds to wind pressure.
Does a Wind Mitigation Inspection Lower Your Insurance Premium?
This is where homeowners should be careful about assumptions.
A wind mitigation inspection itself doesn’t automatically mean your insurance premium will decrease. Instead, the report documents qualifying features of the property. Depending on the home, insurer, policy, and documentation, certain features may qualify for available wind mitigation credits. That’s an important distinction. Two homes on the same street could have very different construction features and therefore different wind mitigation findings.
The goal should be to make sure the insurance company has accurate and current information about your home, rather than assuming that simply ordering an inspection guarantees a particular discount.
Your Roof Can Make a Difference
The roof is one of the most important components documented during a wind mitigation inspection.
The inspector may review the roof covering, roof deck attachment, roof-to-wall connection, roof geometry, and other applicable characteristics. This becomes especially relevant when a homeowner replaces a roof. If your previous wind mitigation inspection was completed before your new roof was installed, the old report may no longer reflect all of the home’s current features. That’s why a roof replacement can be a good time to ask whether an updated wind mitigation inspection should be completed.
Keep your roofing contract, permit information, paid invoices, and other documentation related to the project. Those records can be useful when updating your insurance information.
What About Impact Windows and Hurricane Protection?
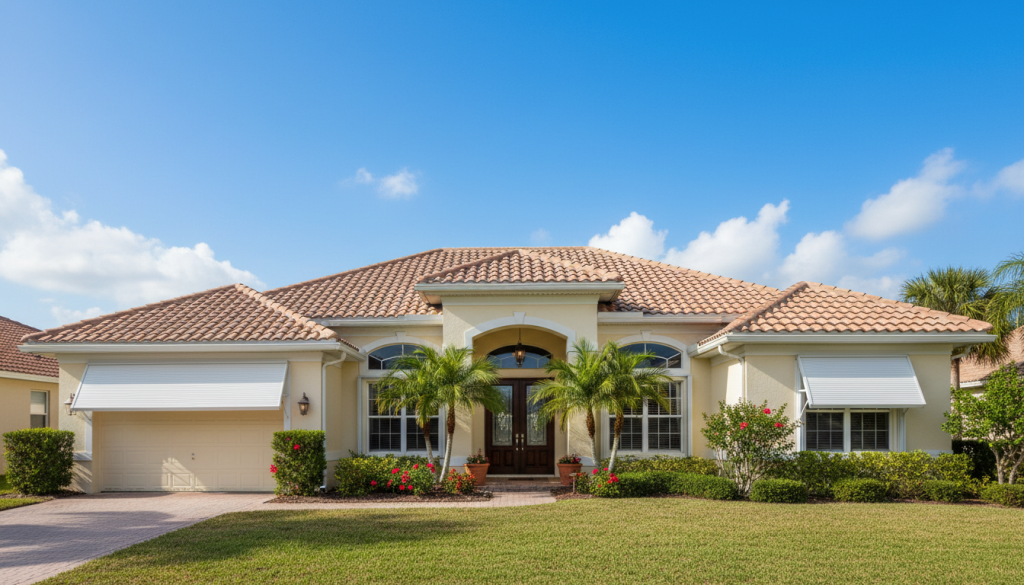
Opening protection is another area that can affect a wind mitigation report. This can include qualifying protection for windows, exterior doors, garage doors, skylights, and other openings, depending on the property and applicable requirements.
One common mistake is assuming that replacing only some windows with impact-resistant products means the entire home qualifies for the same level of opening protection. That isn’t necessarily the case. The inspector needs to evaluate the applicable openings and documentation to determine what can properly be reported.
If you’ve installed impact-resistant windows, doors, shutters, or other hurricane protection since your last inspection, keep the product documentation and permits whenever possible.
When Should You Consider Getting an Updated Inspection?
You don’t necessarily need a new wind mitigation inspection every year. However, there are situations when it makes sense to ask whether an updated inspection could be useful.
Consider reviewing it after:
- Replacing your roof
- Installing impact-resistant windows or doors
- Adding qualifying hurricane shutters or opening protection
- Making structural improvements that may affect wind mitigation features
- Purchasing a home
- Discovering that your current report no longer accurately reflects the property
If you’re unsure whether your existing inspection is still appropriate, your insurance professional can review what you have and help determine whether updated documentation may be worthwhile.
Don’t Throw Away the Report
Once the inspection is completed, keep a copy with your important home records. The report can be useful when reviewing insurance options or changing insurers, and it also gives you a documented snapshot of certain construction features of your home at the time of inspection.
Keep supporting documentation as well, particularly for major improvements. A simple digital folder containing your wind mitigation report, roof documents, permits, receipts, and product information can make things much easier when you need them later.
Wind Mitigation Is Only One Part of Your Insurance Review
A favorable wind mitigation report doesn’t tell you everything you need to know about your homeowners insurance. You should still understand your coverage limits, hurricane deductible, roof provisions, flood exposure, personal property coverage, liability protection, and important exclusions or limitations.
Insurance works best when you’re looking at the entire picture rather than one discount or one number on the policy. That’s especially true in Florida, where the characteristics of the home and the coverage selected can both play important roles in the insurance process.
Have You Made Improvements to Your Home?
If you’ve recently replaced your roof, installed impact windows or doors, added hurricane protection, or made other significant improvements, it may be a good time to review your homeowners insurance information.
At EZ Assurance Group, Inc., we can help you review your current coverage and discuss available insurance options based on your individual property and needs.
EZ Assurance Group, Inc.
3350 SW 148th Ave, Suite 110, Miramar, FL 33027
Phone: (954) 493-1110
Email: info@ezassurancegroup.com
Website: www.ezassurancegroup.com
Contact EZ Assurance Group, Inc. to discuss your Florida homeowners insurance options.
Coverage, eligibility, discounts, credits, deductibles, terms, conditions, exclusions, underwriting requirements, and availability vary by insurer and individual risk. Wind mitigation credits are subject to applicable insurer requirements and supporting documentation. This article is provided for general informational purposes and does not modify or replace the terms of any insurance policy.